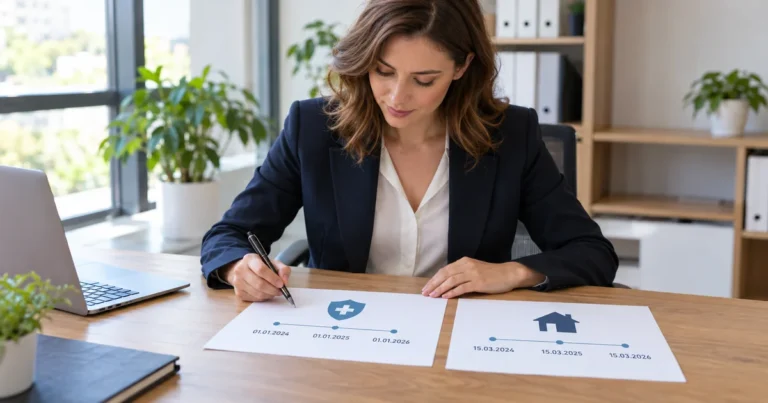
If you don’t know the exact date of the decision in your case, don’t enter the estimated date as a specific date. It’s a good idea to choose the policy term based on information you can verify in your documents and the terms of your specific insurance policy. A mere estimate of when the proceedings will end does not guarantee that coverage will be needed exactly until that date.
Why You Shouldn't Try to Guess the Date of the Decision
The waiting period may not align with the previously agreed-upon schedule. Therefore, the estimated date should not automatically mark the end of the policy. If you do not know the date of the decision, treat it as a circumstance requiring further verification, rather than a fixed date on the calendar.
⚠️ Important: The estimated date is not a definite date.
Insurance coverage is provided under the terms of the contract. The accepted ERGO General Terms and Conditions of Insurance specify that coverage applies to insured events that occur during the insurer’s period of liability. For this reason, you should check the policy and the applicable General Terms and Conditions of Insurance Contractual Commencement of Liability, its end, and the conditions applicable to the given option.
Do not assume that the selected period will be accepted in a specific residency case. Without official evidence pertaining to that case, we cannot promise that the document will be accepted, nor that a single period will be appropriate for every individual. Before making a decision Check the latest official information directly related to your case.
How to Organize the Available Dates
Start by separating the information contained in the documents from your own assumptions. If you have a document or confirmation, check the date on it. If the document specifies a deadline related to your situation, write it down along with the name of the document to avoid relying solely on your memory in the future.
A simple set of conditional steps might be useful:
This classification helps distinguish between facts recorded in documents based on the assumptions. However, it does not determine what policy term will be required in your case. It is intended solely to help you make a more informed decision and reduce the risk that a projection will be treated as confirmed information.
How to Choose an Insurance Term
Selecting the policy term requires balancing two factors: the uncertainty regarding the future course of the case and the terms of the available insurance policy. There is no basis for specifying a single, universal term that would be appropriate for every foreign national awaiting a residence card.
First, determine when you actually need coverage. If you already have a policy, check the expiration date listed on it and the coverage terms described in its General Terms and Conditions. Do not confuse the period stated on the policy with the scope of coverage — The scope, limits, and exclusions are separate elements of the agreement.
Next, consider how long you want to keep the insurance, keeping in mind that you do not know when the case will be resolved. A longer term may reduce the need to purchase coverage again quickly, but it does not guarantee that the document will be accepted or that the proceedings will yield a specific outcome. A shorter term, on the other hand, requires closer monitoring of when the coverage expires.
In Uniqa's General Terms and Conditions, the premium amount depends, among other things, on the insurance period, coverage, and the amounts insured. This means that the contract term should not be analyzed in isolation from the other terms. When comparing the available options, pay attention not only to the duration but also to the scope of coverage you receive and the limits of liability set forth in the contract.
What to Check in the Policy and the General Terms and Conditions
The policy typically outlines the key terms of the agreement; however, the detailed terms and conditions are set forth in the General Insurance Terms and Conditions (GITC) and—depending on the product—in the relevant clauses. The GITC approved by Compensa state that The specific scope of coverage is defined by the clauses, and coverage for medical expenses applies only to stays within Poland. The product name alone is therefore not sufficient to assess the actual scope of coverage.
Before making your choice, be sure to check the following first:
The approved General Insurance Terms and Conditions (GITC) of TUZ Ubezpieczenia precisely define the conditions for the payment of benefits, as well as the limitations and exclusions of liability. This is an important reminder that The mere fact that a policy is in effect does not guarantee a payout. For the benefit to be paid, the event must meet the conditions specified in the contract, and the limitations described therein may also apply.
Limits are also important. In ERGO’s General Terms and Conditions of Insurance, the sum insured represents the limit of liability for a single event and for all events during the insurance period, subject to the applicable sublimits. In Uniqa’s General Terms and Conditions of Insurance, the sum insured, the guarantee amount, and their sublimits constitute upper limit of liability and are reduced by any benefits or compensation paid. Their values are specified in the policy and in the table of options in the General Terms and Conditions.
Don't automatically apply these rules to every offer. Review the documents associated with a specific product and variant, which you are considering. Also check the policy and the applicable General Terms and Conditions to determine when the insurer’s liability begins. Do not base this solely on the fact that you have the document, have filled out the form, or have made a payment.
A Practical Pre-Purchase Checklist
Before signing the contract, take a few specific steps:
This list is not a substitute for the terms of the contract or official information. However, it helps you avoid making a decision based on a single uncertain date.
What to Do Before Your Coverage Expires
If you have a policy, set a reminder before the expiration date listed on it. Don't wait until the last day, to reassess your situation. This is a practical way to make sure you don't miss the deadline and only realize it after the fact.
When reassessing your situation, check to see if any new documents have been issued. If you have a new document or confirmation, check the date listed on it. If the document specifies a date relevant to your situation, compare it to the term of your current policy. If you still do not know the date of the decision, reconsider the coverage period without presenting the forecast as a certainty.
Also, check to see if the next contract covers the necessary scope. The continuity of dates does not automatically imply the continuity of all conditions. A new policy may have different options, coverage, sum insured, sublimits, or exclusions. Evaluate each policy based on its own documentation.
Common Mistakes
The first mistake is to enter the expected completion date of the case as a definite deadline. That date may later serve as the basis for further assumptions, even though it does not come from the document.
The second mistake is to focus solely on the policy term. The protection period is just one of the parameters. Equally important are the scope, limits, sublimits, payout conditions, and exclusions.
The third mistake is assuming that having a policy means you’re covered in every situation. The insurer’s liability depends on the terms of the contract, and the specific rules may be set forth in the General Insurance Terms and Conditions (GITC) and in additional clauses.
The fourth mistake is automatically assuming that a new policy takes effect simply because the form has been filled out, the document has been issued, or payment has been made. Check the effective date of coverage in the policy and the applicable General Terms and Conditions.
The fifth mistake is putting off reviewing your documents again. If you have a policy, use the reminder before its expiration date and reassess your situation well in advance.
FAQ
Can I enter the expected date of the decision as a firm deadline?
No. If you do not know the exact date of the decision, do not present your assumptions as confirmed information. If you have a document or confirmation, check the date on it. With regard to the requirements, verify the current, official information directly related to your case.
Does a longer policy guarantee that the document will be accepted?
This cannot be guaranteed based solely on the duration of the insurance coverage. A longer period of time is no guarantee of acceptance or a specific outcome of the case. When making your choice, take the terms of the agreement into account, and evaluate the requirements solely based on current, official information that directly pertains to your case.
Is the date on the policy sufficient to determine the start of coverage?
You should not base such a conclusion solely on a single date. If you have a policy, check the information listed on it, and then read the relevant General Terms and Conditions. The contractual commencement of liability is determined by the terms of the contract, which may include more items than just the period specified on the document.
Is the sum insured available separately for each incident?
This depends on the terms of the specific contract. In ERGO’s approved General Terms and Conditions of Insurance, the sum insured represents the limit for a single event and all events during the insurance period, subject to sub-limits. In Uniqa’s approved General Terms and Conditions of Insurance, the sums insured and sub-limits are the maximum limits of liability and are reduced by the amounts paid out. Always check the rules for your variant.
What should you do if your current policy is about to expire?
If you have a current policy, check the expiration date listed on it and set an early reminder. For new documents, verify the dates listed on them. Next, carefully review the term, coverage, limits, and exclusions in the new policy—don’t automatically assume that the terms will remain the same.
 Polish
 English
 Ukrainian
 Spanish
 Turkish
 Russian
 Indonesian
 Vietnamese